
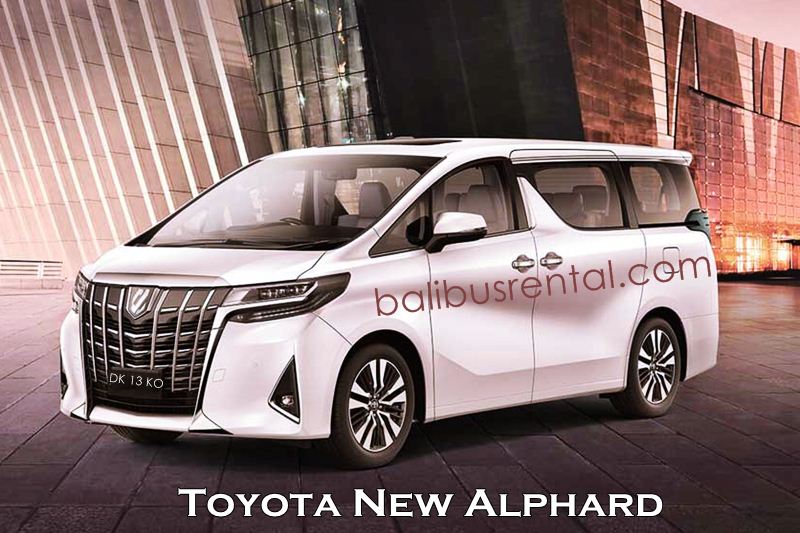


Toyota New Alphard 6 Seats Hire Bali
The All New Toyota Alphard Rental In Bali goes straight to the top of the class in the luxury MPVs segment. It is not only an MPV for the well-heeled to enjoy the back seats, but it’s also for those who are willing to fork out a little more over the regular MPVs to own and drive one of the biggest cars on the roads out there, while carrying their family in top-of-the-line comfort.
The biggest draw for Toyota Alphard is its cabin. Thanks to the big doors up front and rear, access is extremely easy. Inside, occupants will be treated to a sea of suede, diamond patterned leather, and shiny reflective surfaces. Classy.
We are happy to explain and show you the beauty of Bali and the culture. We show you the real life of Bali, the friendly Balinese people, traditional Balinese architecture, Bali panoramic view, beaches, temples, Dance, low cost shopping, and much more. You can also design your own tour.
Breaking News:
Why Japan’s markets matter so much for America
Tuesday | September 22, 2026
From surging bond yields to unprecedented US involvement in efforts to stabilize the yen, Japan’s financial markets are undergoing one of their most consequential transformations in decades. The changes are being closely watched by investors around the world because Japan is not only a major economy but also one of the largest pools of global savings and a major holder of overseas financial assets.
The immediate pressure is visible in Japan’s government bond market. Yields have climbed to levels not seen in roughly three decades as investors adjust to higher inflation, rising Bank of Japan interest rates and growing concerns about the government’s plans for tax cuts and increased spending. At the same time, the yen remains volatile despite a historic joint intervention by Washington and Tokyo designed to prevent the currency from falling too far.
The developments are closely connected. A weaker yen can contribute to imported inflation, while higher Japanese interest rates can make domestic assets more attractive to Japanese investors. If investors begin moving large amounts of money back into Japan, they could reduce demand for overseas assets, including US Treasury securities.
That possibility has made Japan’s financial policy a matter of concern in Washington.
Japan is the largest foreign holder of US Treasury securities, giving Japanese investors an important role in the global market for US government debt. A large-scale shift by Japanese investors away from Treasuries could put downward pressure on Treasury prices and push yields higher at a time when US borrowing costs are already elevated.
US Treasury Secretary Scott Bessent has therefore become unusually involved in Japan’s currency and monetary-policy debate. According to Reuters, Japanese Finance Minister Satsuki Katayama sought US assistance in June as the yen was coming under severe pressure. Bessent privately urged Tokyo to address its fiscal policy and encouraged a tighter monetary-policy stance before Washington supported intervention.
That intervention eventually took place in late July, when the United States and Japan coordinated efforts to support the yen. The operation was extraordinary because Washington rarely intervenes directly in foreign-exchange markets to support another major currency. Bessent subsequently said he would not hesitate to repeat the intervention if necessary.
The yen has since remained above its extreme lows, although it has weakened again. Bessent said in late August that recent movements in the currency were relatively contained and did not constitute the kind of disorderly market conditions that had prompted the earlier intervention.
The situation has become even more complicated following the Bank of Japan’s latest rate increase.
Bond market
Stubborn inflation, higher interest rates and growing concerns about government borrowing have pushed bond yields higher across many major economies. Japan, however, has been undergoing a particularly dramatic adjustment because it is emerging from an extraordinarily long period of near-zero interest rates.
On September 18, the Bank of Japan raised its benchmark interest rate from 1% to 1.25%, the highest level in 31 years. The move marked another step away from the ultra-loose monetary policy that had defined Japan’s economy for decades.
The change has profound implications for the country’s bond market.
When bond prices fall, their yields rise. Investors have been selling Japanese government bonds as they reassess the outlook for inflation, interest rates and government borrowing. The yield on Japan’s 10-year government bond has reached its highest level in about 30 years, while longer-term borrowing costs have also climbed sharply.
The adjustment represents a major reversal of the conditions that prevailed after Japan spent decades fighting deflation. For much of that period, extremely low Japanese interest rates encouraged investors to seek higher returns abroad.
Now, the direction of travel is changing.
Higher Japanese interest rates mean domestic bonds can offer investors substantially more income than they did in the past. That could gradually reduce the incentive for Japanese institutions and households to send savings overseas.
The change is particularly important because Japanese investors have accumulated enormous holdings of foreign assets over decades of low domestic yields. Japan’s investors hold roughly $2.5 trillion in US financial assets, according to recent estimates cited by The Wall Street Journal.
Even a relatively small reallocation of that money could influence global markets.
The effect does not necessarily require Japan to deliberately dump US Treasuries. Japanese pension funds, banks, insurers and other investors may simply decide that the improved returns available at home justify buying more Japanese assets and reducing new purchases of foreign securities.
That could gradually increase borrowing costs in the United States and other markets.
The issue is especially sensitive because US Treasury yields have also risen sharply. The benchmark 10-year Treasury yield recently reached around 5%, its highest level in many years, adding pressure to mortgages, corporate borrowing and government financing costs.
Japan is therefore caught between two competing forces. Higher interest rates can help support the yen and make domestic assets more attractive, but they can also increase the cost of servicing Japan’s enormous government debt.
That makes fiscal policy crucial.
Investors are increasingly scrutinizing Prime Minister Sanae Takaichi’s economic agenda, including proposals involving tax cuts and increased government spending. The concern is that additional fiscal stimulus could require even greater government borrowing at precisely the moment when investors are demanding higher returns to hold Japanese debt.
Reuters reported that Bessent has pressed Japanese officials to restrain spending partly because Washington is worried that a Japanese bond sell-off could spill over into the US Treasury market.
The result is a difficult policy balancing act for Tokyo. The government wants to support households and the broader economy, while the central bank is attempting to normalize monetary policy and investors are demanding greater compensation for holding long-term government bonds.
Why Japanese bond yields matter to the world
Japan’s bond market might seem distant from American households or investors, but the two markets are deeply connected.
For years, extremely low Japanese interest rates encouraged investors to seek better returns in the United States, Europe, Australia and emerging markets. Japanese money became an important source of demand for foreign bonds and other assets.
As Japanese yields rise, that calculation changes.
An investor who once had little choice but to seek returns overseas can increasingly find attractive opportunities at home. If enough investors make that adjustment, demand for foreign bonds could decline.
That can push foreign bond prices lower and yields higher.
For the United States, this matters because higher Treasury yields translate into higher financing costs across the economy. Treasury yields influence mortgage rates, corporate borrowing costs, consumer loans and the government’s own debt-servicing expenses.
The process can therefore become self-reinforcing: higher Japanese yields encourage some capital to return home, reduced overseas demand contributes to higher US yields, and higher US borrowing costs make financial conditions tighter for American businesses and households.
There is also a psychological effect. Investors around the world have treated Japanese government bonds as one of the safest and most liquid markets for decades. A sustained change in that market can force global asset managers to reconsider how they allocate capital.
The yen
The currency market adds another layer of complexity.
The yen suffered a dramatic decline against the dollar earlier this year, eventually prompting coordinated intervention by Japan and the United States. The intervention helped drive the yen roughly 5% higher in late July and early August, but the currency has struggled to maintain those gains.
The fundamental problem is that the yen remains caught between Japan’s changing monetary policy and the country’s fiscal outlook.
Higher Japanese interest rates normally make the yen more attractive because investors can earn greater returns on yen-denominated assets. But if markets believe the Japanese government will continue running large deficits and issuing substantial amounts of debt, that can undermine confidence in the currency.
The United States has a particular interest in preventing an uncontrolled decline in the yen.
If the yen becomes extremely weak, Japanese authorities may be tempted to sell foreign assets, including US Treasuries, in order to obtain dollars that can then be converted into yen. A significant Treasury liquidation could push US bond prices lower and yields higher.
That is one reason analysts see a connection between Washington’s currency diplomacy and its concerns about the Treasury market.
At the same time, Washington has to consider the opposite risk.
A rapidly strengthening yen could trigger a major unwinding of the so-called yen carry trade.
For decades, investors have borrowed yen at extremely low interest rates and used the money to purchase assets offering higher returns elsewhere. The strategy works as long as the yen remains relatively cheap or stable and the interest-rate differential remains favorable.
But if the yen suddenly rises, the economics can reverse.
An investor who borrowed ¥1 billion when the currency was weak could face a significantly larger dollar-equivalent liability if the yen strengthens sharply. If Japanese interest rates are rising at the same time, the cost of maintaining the trade increases further.
That can force investors to sell assets purchased with borrowed yen.
Those assets can include US stocks, Treasury securities, emerging-market bonds, commodities and other risk-sensitive investments.
The yen carry trade is therefore an important transmission mechanism between Japanese monetary policy and markets thousands of miles away. Recent analysis has estimated that the strategy, broadly defined, involves enormous amounts of capital, although estimates vary considerably depending on what positions are included.
A delicate balance for Washington
This leaves US policymakers facing an unusually complicated set of incentives.
Washington does not want the yen to weaken so dramatically that Japanese authorities are forced into large-scale asset sales to defend their currency. Such selling could put additional upward pressure on US Treasury yields.
But policymakers also have reasons to avoid a sudden, disorderly strengthening of the yen. A sharp appreciation could destabilize the carry trade and encourage investors to liquidate positions across global markets.
In other words, the United States has an interest in stability rather than simply a stronger or weaker yen.
That helps explain why Bessent’s involvement has attracted so much attention. His approach has extended beyond conventional diplomatic discussions and into the intersection of currency policy, Japanese fiscal policy, monetary policy and the US Treasury market.
Reuters reported that Bessent’s pressure on Tokyo included calls for greater fiscal discipline and a higher Japanese interest-rate path.
The situation also illustrates how closely intertwined the world’s major economies have become.
Trump and Takaichi
The issue is particularly relevant this week as President Donald Trump and Japanese Prime Minister Sanae Takaichi are expected to meet in New York on September 22 during the UN General Assembly.
Their meeting comes at a particularly sensitive moment for the US-Japan economic relationship, with currency policy, interest rates, fiscal spending and investment all connected.
For Tokyo, the challenge is to stabilize the yen without creating excessive financial stress. The government also has to manage its debt burden while responding to demands for economic support.
For Washington, the priority is broader. US officials want financial stability in Japan partly because a major disruption in Japanese markets could quickly affect American bond markets.
That makes the US-Japan financial relationship much more than a bilateral currency issue.
It is increasingly a question of how the world’s largest government bond markets interact with one another.
What investors are watching
Investors are now watching several indicators simultaneously.
The first is the trajectory of Japanese government bond yields. If yields continue rising rapidly, markets may begin pricing in a much more fundamental change in Japan’s fiscal and monetary regime.
The second is the yen. A renewed decline could increase pressure for further intervention, while a sudden rebound could raise concerns about an unwinding of carry trades.
The third is the Bank of Japan. The September rate increase to 1.25% has reinforced expectations that Japan’s era of ultra-cheap money is coming to an end, although the pace of further increases remains uncertain.
The fourth is government spending. Investors will be watching whether Takaichi’s administration follows through on its expansionary plans and how those plans will be financed.
And the fifth is the US Treasury market.
Any significant repatriation of Japanese capital could add to existing pressure on US government debt. Conversely, a disorderly sell-off in global markets triggered by a rapid yen appreciation could create a different set of problems for American investors.
The result is a remarkably narrow path for policymakers.
Japan needs to normalize interest rates after decades of extraordinary monetary accommodation, stabilize a vulnerable currency and reassure investors about its fiscal position. The United States wants those changes to happen without triggering a destabilizing wave of capital movements into or out of Japanese and US markets.
That is why developments in Tokyo are being watched so closely on Wall Street and in Washington.
Japan’s bond and currency markets are no longer simply domestic matters. The country sits at the center of a vast network of global capital flows, and changes in the value of the yen or the price of Japanese government debt can affect investment decisions far beyond Asia.
The deeper significance of the current turmoil is therefore not simply that Japanese borrowing costs are rising or that the yen has become volatile. It is that one of the world’s most important financial systems is moving away from the ultra-low-rate environment that shaped global markets for decades.
The transition is likely to be gradual in some areas and abrupt in others. But as Japanese yields rise, the yen shifts and investors reconsider where to place their money, the consequences will increasingly be felt in US Treasuries, global bond markets, stock markets and borrowing costs for businesses and households around the world.
Special Price for Rental Toyota New Alphard
|
Type of usage
|
Charter 10 hours
|
Charter 5 hours
|
Extra hour
|
|
USD
|
USD 195
|
USD 150
|
USD 20
|
The price include:
- Excellent Luxury transportation
- Fit for 6 persons
- AC and TV Karaoke
- Power steering
- Great performance
- Comfortable drive
- Friendly Driver
REMARKS:
- Charter Vehicle the price is calculated per day up to 10 hours, with the payment of overtime hours (in 1 hour of overtime) x 10% charter.
- Charter Vehicle the prices already include the fuel and driver services.
- Charter Vehicle Half day/ Hourly only valid for areas of Kuta, Legian and Nusa Dua.
- Charter Vehicle Rates above do not apply to routes Amed, Tulamben, Candi Dasa (Karangasem), Lovina (Singaraja), and Negara (Jembrana).
- Charter Vehicle the price above is valid until 31 April 2027.
- Personal expenses
- Gratuities.
Your request or reservation is absolutely secure, all personal data is encrypted and will be processed in a secure way through secure email. We take the privacy of your personal data very seriously. Your personal information will only be used to process your booking.